

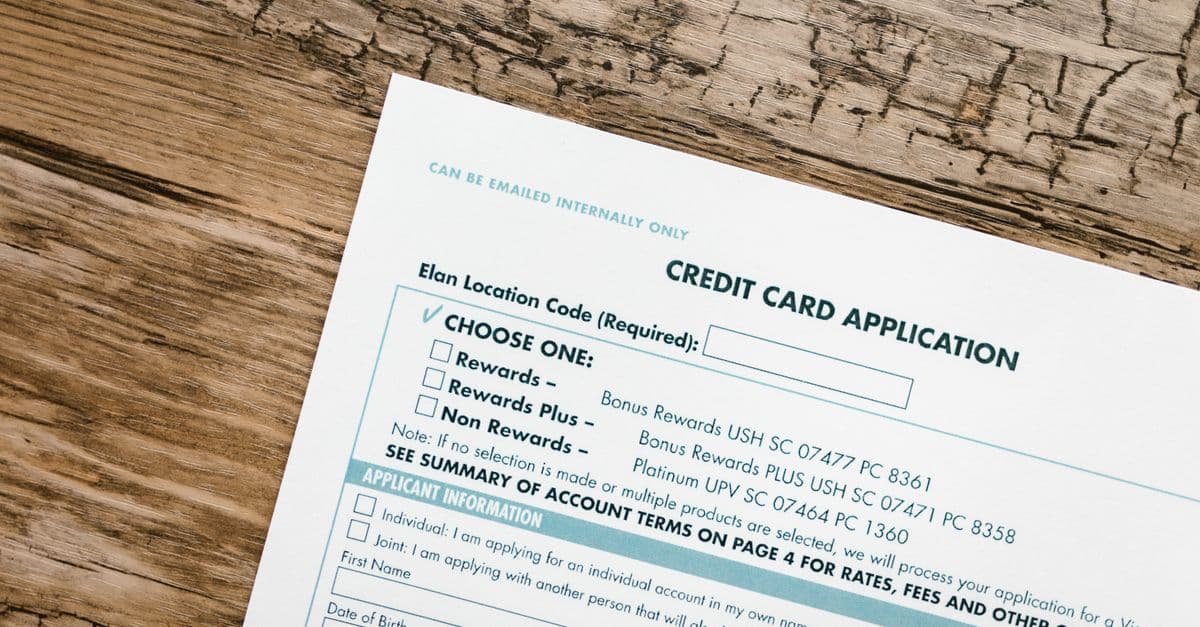
Consumer Loan Application Risk Assessment
Evaluate consumer loan applications with systematic creditworthiness and risk analysis
What You Can Do
You can process consumer loan applications using structured financial analysis that combines quantitative metrics (credit scores, debt-to-income ratios, payment history) with qualitative factors (employment stability, loan purpose, market conditions). Claude synthesizes application data against regulatory requirements and your institutional risk appetite to produce defensible lending decisions, justify decline determinations to applicants in compliant language, and stress-test applications against changing rate environments or income verification updates.
Features
combines credit score, payment history, and derogatory marks into creditworthiness assessment
evaluates debt capacity and repayment likelihood using income verification and existing obligations
assesses loan-to-value ratios and collateral liquidation risk for secured lending products
flags compliance concerns and generates decision language defensible to auditors
evaluates competing loan products and terms for a single applicant
produces compliant explanation language for applicant communications
recalculates risk metrics under alternative rate or income scenarios
synthesizes risk patterns across similar application groups
Example Output
Example 1: Approval Recommendation
Applicant: Sarah Chen, $65K annual income, 720 credit score
Assessment:
- DTI Ratio: 28% (within 43% threshold)
- Credit History: 8 years, no delinquencies, 2 hard inquiries (6 months)
- Employment: 4-year tenure, stable industry
- Recommendation: ✓ APPROVE for $18,000 auto loan at standard rate. Risk profile aligns with institution appetite.
Example 2: Conditional Approval with Documentation
Applicant: Marcus Rodriguez, $52K annual income, 680 credit score
Risk Factors:
- Recent mortgage forbearance (resolved, 12 months ago)
- DTI Ratio: 41% (near threshold)
- Missing 2 months recent pay stubs
Recommendation: ✓ CONDITIONAL APPROVE pending: (1) verification of last 2 months employment income, (2) written explanation of forbearance. Reassess DTI after verification.
Example 3: Decline with Compliant Messaging
Applicant: James Patterson, $48K annual income, 620 credit score
Decline Factors:
- DTI Ratio: 51% (exceeds 43% threshold)
- 3 collections accounts within 24 months
- Employment tenure: 6 months (insufficient history)
Recommendation: DECLINE. Compliant Notice Language: "Your application did not meet our current lending criteria based on debt obligations relative to income and recent credit history. You may reapply after 12 months of stable employment."
What's Included
- SKILL.md instruction file: structured prompts and decision frameworks for loan application evaluation
- Credit Analysis Checklist: standardized credit score interpretation, payment history review, and derogatory mark assessment
- Debt-to-Income Calculation Template: income verification worksheet and existing obligation inventory with threshold comparison
- Regulatory Compliance Markers: required disclosures, ECOA/Fair Lending flags, and state-specific lending regulation reminders
- Decline Decision Language Library: compliant messaging templates for different decline reasons and scenarios
Who It's For
- Loan Officers — streamline application screening and generate defensible approval/decline recommendations
- Credit Analysts — accelerate initial application assessment before credit committee review
- Underwriters — document creditworthiness analysis and stress-test applications against changing conditions
- Compliance Specialists — verify decision language and flag regulatory risk in loan portfolios
- Branch Managers — review portfolio risk trends and justify lending decisions to auditors
Best For
- Initial consumer loan application screening and triage
- Comparison of competing loan products and terms for a single applicant
- Documentation of creditworthiness analysis for compliance file
- Stress-testing applications against rate changes or income verification updates
- Generating compliant decline explanations for applicant communications
- Portfolio risk cohort analysis across similar application profiles
You might also like
You can map regulatory requirements against your institution's filings, identify compliance gaps with specificity, and generate structured remediation plans with timelines and accountability assignments. Claude helps you create audit-ready documentation that demonstrates systematic control adherence, reducing manual review time and ensuring consistent compliance assessment across complex banking regulations.
 by eternaljust
You can conduct comprehensive wealth structure reviews that evaluate tax efficiency across jurisdictions, identify asset protection gaps, and align structures with succession and legacy objectives. The skill helps you map existing entity layers, spot redundancies, model optimization scenarios, and present data-driven recommendations that balance regulatory compliance with client risk tolerance and control preferences.
by eternaljust
This skill systematically reviews multi-document SBA loan applications against program-specific compliance standards. You can cross-reference personal financial statements, tax returns, and business financials for consistency; verify all required forms are present and completed; flag missing collateral documentation; and identify eligibility issues—all before sending applications to the SBA for guarantee review. By catching deficiencies early, you eliminate costly resubmissions and accelerate funding timelines.
by eternaljust
You get proven templates, decision trees, and frameworks to design complete business automation systems from scratch. Cut implementation time by 70%, reduce manual work by 80%, and build processes that scale across your entire organization without custom coding or guesswork.
by eternaljust
Analyze transaction networks, corporate structures, and beneficial ownership relationships to uncover indirect sanctions exposure and evasion methodologies. You can flag structuring patterns, shell entity networks, trade-based money laundering indicators, and entity relationship anomalies that standard list-matching tools miss. The skill helps you prioritize cases for enhanced due diligence and escalation by identifying geographic, sectoral, and transactional red flags consistent with known sanctions evasion tactics.
by eternaljust
Conduct thorough, documented customer risk assessments using structured compliance decision trees aligned with FinCEN, OFAC, and BSA standards. You'll evaluate customer information, identify regulatory red flags, determine appropriate risk classifications, and generate audit-ready documentation that demonstrates defensible decision-making during regulatory examinations. This skill accelerates due diligence while reducing compliance gaps and creating the paper trail regulators expect.
by eternaljust
You systematically evaluate consumer credit applications by synthesizing credit reports, income documentation, employment history, and behavioral indicators into quantified risk assessments. The framework generates defensible approval/decline recommendations tiered by risk level (prime, near-prime, subprime), incorporates Fair Lending Act compliance checks, and documents decisions that withstand regulatory examination and customer appeals.
by eternaljust
You can analyze entire Android Jetpack Compose codebases or specific modules to uncover architectural and performance issues. The skill scans your source code against four critical categories—performance, state management, side effects, and composable API quality—scoring each from 0–10 and delivering an evidence-based markdown report that prioritizes the most impactful fixes first.
by eternaljust